报告摘要
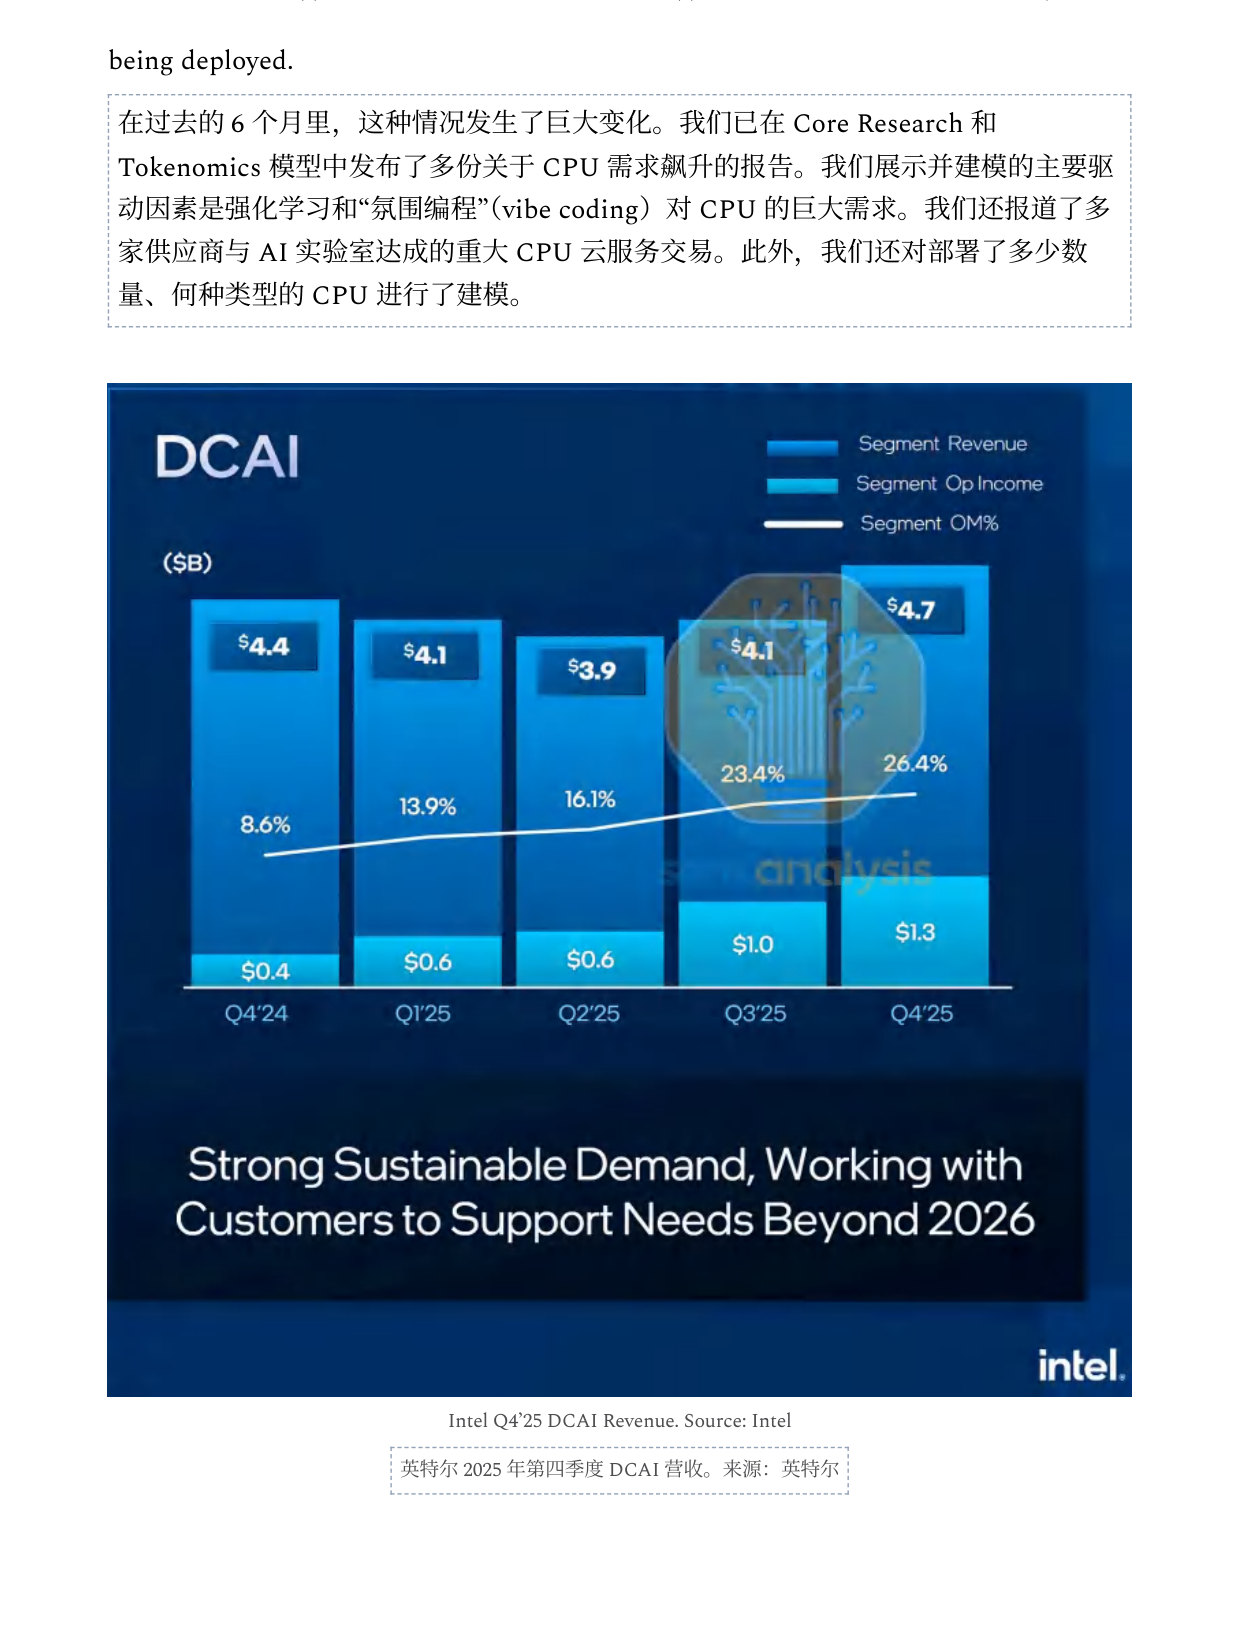
Since 2023, the datacenter story has been simple. GPUs and networking are king. The arrival and subsequent explosion of AI Training and Inference have shifted compute demands away from the CPU. This meant that Intel, the primary supplier of server CPUs, failed to ride the wave of datacenter buildout and spending. Server CPU revenue remained relatively stagnant as hyperscalers and neoclouds focused on GPUs and datacenter infrastructure. 自2023年以来,数据中心的故事一直很简单:GPU 和网络是核心。AI 训练与推理的出现及随后的爆发式增长,将计算需求从 CPU 转移。这意味着服务器 CPU 的主要供应商英特尔未能赶上数据中心建设和支出的浪潮。随着超大规模云厂商 (Hyperscalers)和新型云服务商(Neoclouds)将重点转向 GPU 和数据中心基础设施,服务器 CPU 的营收一直处于相对停滞状态。
At the same time, the same hyperscalers have been rolling their own ARM-based datacenter CPUs for their cloud computing services, closing off a significant addressable market for Intel. And within their own x86 turf, Intel’s lackluster execution and uncompetitive performance to rival AMD has further eroded market share. Without a competent AI accelerator offering, Intel was left to tread water while the rest of the industry feasted. 与此同时,这些超大规模云厂商一直在为自己的云计算服务开发基于 ARM 架构的数据中心 CPU,从而封闭了英特尔的一个重要潜在市场。而在其自身的 x86领地内,英特尔乏善可陈的执行力以及面对竞争对手 AMD 时缺乏竞争力的性能,进一步侵蚀了其市场份额。由于缺乏有竞争力的 AI 加速器产品,当行业其他公司大快朵颐时,英特尔只能在原地踏步。
报告前五页预览
本文来自知之小站
报告已上传百度网盘群,限时10元即可加入
(如无法加入或其他事宜可联系zzxz_88@163.com)